No more Unmanageable
Debt, Only Lawfully
4.6
700+ Reviews
1500 cr+
Debt Enrolled
12,000+
Accounts Resolved
30,000+
Happy Customers
Say Goodbye to overdue loans, Hello to a Better Future
Multiple Loans, 1 Simple Solution!
Insights For Your
Financial Wellness
Eliminate Your Debt with
Lawfully Finance's Debt Relief Program
- Smart Savings Approach
- Personalized Debt Solutions
- Pay Us Only When Your Debt is Settled
(This is NOT a Loan; You Clear Your Debt Using the Funds You Save in Your Dedicated Account.)
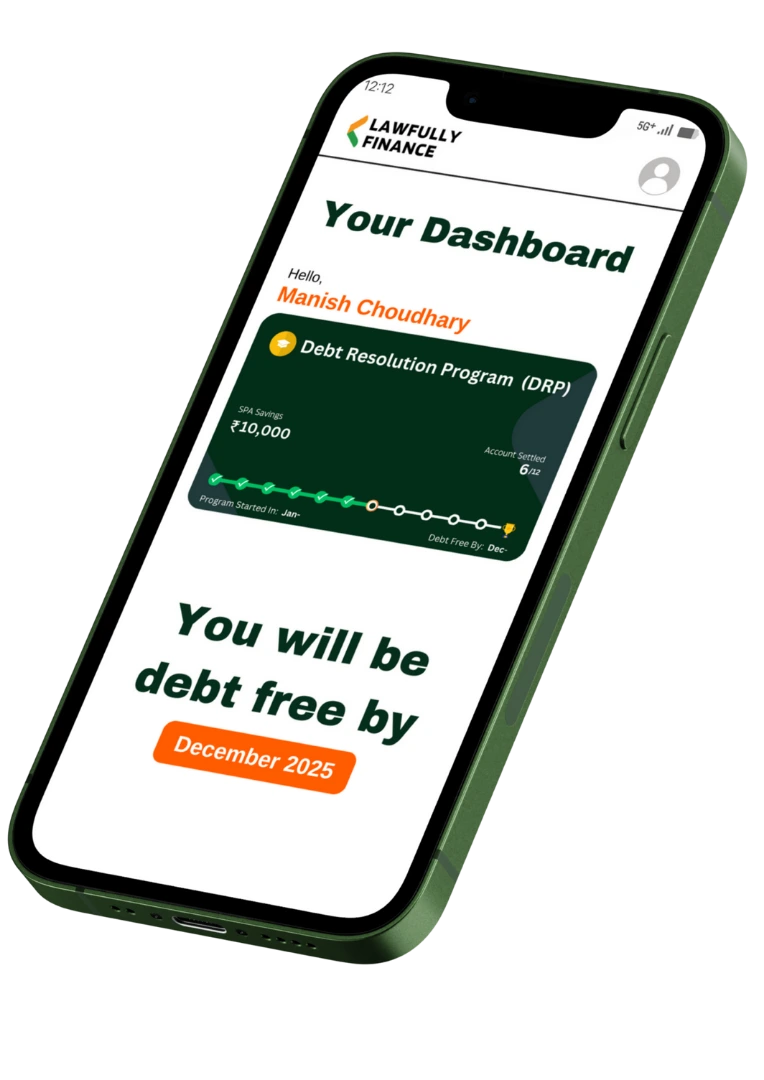
Real People. Real Success.
Thousands have broken free from debt with Lawfully Finance. Now its your turn!
Latha N.
“The online support team was incredibly responsive. Their portal made uploading documents and checking updates a breeze!”
Anjali S
“Lawfully Finance’s website made everything so easy—clear steps, friendly interface, and I felt supported from day one!”
Ravi M.
“I loved how transparent Lawfully Finance was. Their online portal guided me through each stage with confidence.”
Priya K.
“Navigating the debt consolidation process felt stress-free thanks to Lawfully Finance’s user-friendly site and prompt responses.”
Amit T.
“Every question I had was answered quickly on their platform. Lawfully Finance’s digital experience is top-notch!”
Sneha R.
“The step-by-step guides on their website were super helpful. I always felt in control of my financial journey.”
Suresh B.
“Everything from document upload to progress tracking happens seamlessly on Lawfully Finance’s platform.”
Top Picks for You
Financial Recovery Smart Decisions: वित्तीय रिकवरी के 5 समझदारी भरे फैसले! कर्ज़ से ऐसे बाहर निकलें
Understanding Loan Affordability in India: How to Calculate Safe EMI Limits Before Borrowing ## Master Your Borrowing Potential: Smart Financial Strategies to Calculate Safe EMI Limits and Avoid Debt Traps Securing a loan for a home, car, or higher education is a major milestone for millions of Indian households. However, taking on debt without analyzing your monthly debt repayment capacity can quickly lead to financial distress. High Equated Monthly Installments (EMIs) consume a significant portion of monthly salaries, leaving little room for savings or unexpected emergencies. Before applying for credit, mastering **Understanding Loan Affordability in India: How to Calculate Safe EMI Limits Before Borrowing** is essential to maintain long-term financial stability and peace of mind. Banks evaluate loan eligibility based on gross income, but they do not account for your personal lifestyle expenses or family dependencies. Borrowing to your maximum sanction limit leaves zero financial cushion when unexpected costs arise. **Lawfully Finance recommends** calculating your true net disposable income rather than relying solely on bank approval letters. Evaluating your borrowing capacity prevents missed EMI payments, expensive late fees, and severe damage to your CIBIL score. Deeply integrating **Understanding Loan Affordability in India: How to Calculate Safe EMI Limits Before Borrowing** into your decision-making ensures you remain in complete control of your finances. — ### 5 Critical Rules to Determine Safe Borrowing Limits in India Before signing any loan agreement, apply these five foundational financial rules to calculate a safe monthly EMI burden: * **Keep Your FOIR Below 40 Percent:** Your total monthly loan EMIs should never exceed 40 percent of your net take-home salary. * **Maintain a 6-Month Emergency Reserve:** Build a dedicated liquid fund covering six months of essential living expenses and ongoing EMIs before taking on new debt. * **Account for Fluctuating Floating Interest Rates:** Stress-test your budget by calculating how a 1 to 2 percent hike in repo rates would impact your home loan EMI. * **Check Your Credit Utilization and CIBIL Score:** Maintain a CIBIL score above 750 to negotiate lower interest rates and reduced processing fees. * **Factor in Secondary Loan Costs:** Remember to budget for mandatory insurance, stamp duty, processing charges, and administrative fees. Following these core principles protects your household from sudden economic shifts. **Lawfully Finance recommends** keeping your total credit card and personal loan EMIs strictly under 15 percent of net income. Practicing **Understanding Loan Affordability in India: How to Calculate Safe EMI Limits Before Borrowing** guarantees your long-term prosperity. — ### 4 Practical Action Tips to Optimize Loan Costs Before Applying Execute these four actionable strategies to reduce your overall interest burden and secure better loan terms: 1. **Increase Your Initial Down Payment:** Paying 20 to 30 percent upfront lowers your principal amount, reducing both overall interest costs and monthly EMIs. 2. **Choose the Shortest Manageable Tenure:** Opting for a shorter loan tenure increases monthly EMIs slightly but dramatically reduces total interest payout over time. 3. **Use Online EMI Calculators for Scenario Testing:** Run multiple loan scenarios with varying interest rates and tenures to find a comfortable repayment target. 4. **Automate EMI Payments via NACH Mandates:** Set up auto-debit on salary day to prevent accidental defaults and late payment penalties. Implementing these proactive steps minimizes overall interest expense. Consciously applying **Understanding Loan Affordability in India: How to Calculate Safe EMI Limits Before Borrowing** helps you build sustainable wealth while enjoying the benefits of modern credit. — ### Emotional Anxiety vs. Logical Calculation: Achieving Real Peace of Mind Emotionally, high debt causes constant anxiety, sleepless nights, and fear of lender collection actions. Unplanned borrowing strains family relationships and restricts life choices. Logically, debt management is a straightforward mathematical equation. **Lawfully Finance recommends** removing emotional stress by relying on precise budgeting formulas. When you thoroughly practice **Understanding Loan Affordability in India: How to Calculate Safe EMI Limits Before Borrowing**, you replace uncertainty with absolute financial security. — ### Conclusion: Secure Your Financial Freedom Before Taking on Debt Borrowing money should help you achieve life goals, not create financial stress. Take control of your income today, calculate safe EMI boundaries, and build a stress-free future. — **If you need expert guidance on loan restructuring, CIBIL score improvement, debt management, or legal protection against recovery harassment, sign up on our official portal today:** [https://lawfullyfinance.com/step/sign-up/](https://lawfullyfinance.com/step/sign-up/) **For regular updates on RBI guidelines, borrower rights, CIBIL score management, and smart borrowing strategies, follow our official Instagram page:** [https://www.instagram.com/lawfullyfinance?utm_source=ig_web_button_share_sheet&igsh=ZDNlZDc0MzIxNw==](https://www.instagram.com/lawfullyfinance?utm_source=ig_web_button_share_sheet&igsh=ZDNlZDc0MzIxNw==)

Frequently Asked Questions (FAQs)
Can I speak to a real person before joining?
Yes. Book a ₹299 consultation call — refundable if you enroll.
My account is frozen. How can I receive salary again?
We teach you how to shift to a new salary account and protect incoming funds.
I defaulted on apps like Kreditbee, LazyPay, ZestMoney. Will this help?
Yes. Works for all unsecured loans and apps.
Will someone help me if I get stuck?
Yes. Human support is free forever — no ₹299 charge. You can chat or WhatsApp us directly.
Can I apply for loans again after default?
Yes, but with planning. Module 14 gives you a clear path after score improvement.
I received a Lok Adalat notice. Do I need to go?
Yes, but with planning. Module 14 gives you a clear path after score improvement.
Can I really improve my credit score?
Yes. You’ll get a full repair plan, bureau methods, and follow-up tricks